Dubai Short-Term Rental Operators Pivot to Monthly Stays After Regional Shock
A sudden February booking collapse wiped out March travel in Dubai. Six months later, operators are rebuilding occupancy by swapping high tourist rates for monthly stays.
When regional skies darken over the Persian Gulf, short-term rental calendars do not merely show empty slots; they clear out with mechanical, ruthless velocity. On February 28, 2026, property managers across Dubai watched their booking dashboards turn red as an unprecedented cancellation surge wiped out thousands of reservations in a matter of hours. Regional tensions had disrupted flight paths across the Middle East, transforming what was meant to be the crown-jewel stretch of the emirate’s winter season into an operational nightmare.
The figures recorded by short-term rental analytics provider AirDNA caught the exact scale of the initial shockwave: 8,450 cancelled nights in a single twenty-four-hour window on February 28, compared to a baseline average of approximately 3,100 nightly cancellations during the rest of that month. By the time the immediate impact registered, the cancellation rate across the United Arab Emirates reached 43.8 percent, hitting March bookings hardest and sending a tremor through the city’s vast network of hosts, property managers, and real estate investors.
Six months later, as Dubai enters its high season, the immediate panic has passed, but the market left behind bears little resemblance to the environment of early 2025. Occupancy figures have pulled back from the edge, yet average daily rates remain subdued, booking windows have collapsed to last-minute lead times, and professional operators are quietly re-engineering their core business models. What unfolded in Dubai during 2026 offers a stark, documented lesson in how a major global short-term rental market behaves when a sudden demand shock hits an existing supply overhang.
What happened
The immediate catalyst was a sharp escalation in Middle East geopolitical tensions in late February 2026 that threw international air travel into disarray. According to data published by AirDNA, the surge in travel cancellations hit short-term rentals across the United Arab Emirates almost instantly. The spike in cancellations concentrated heavily on stays scheduled for March, traditionally one of the highest-revenue months on the Dubai hospitality calendar.
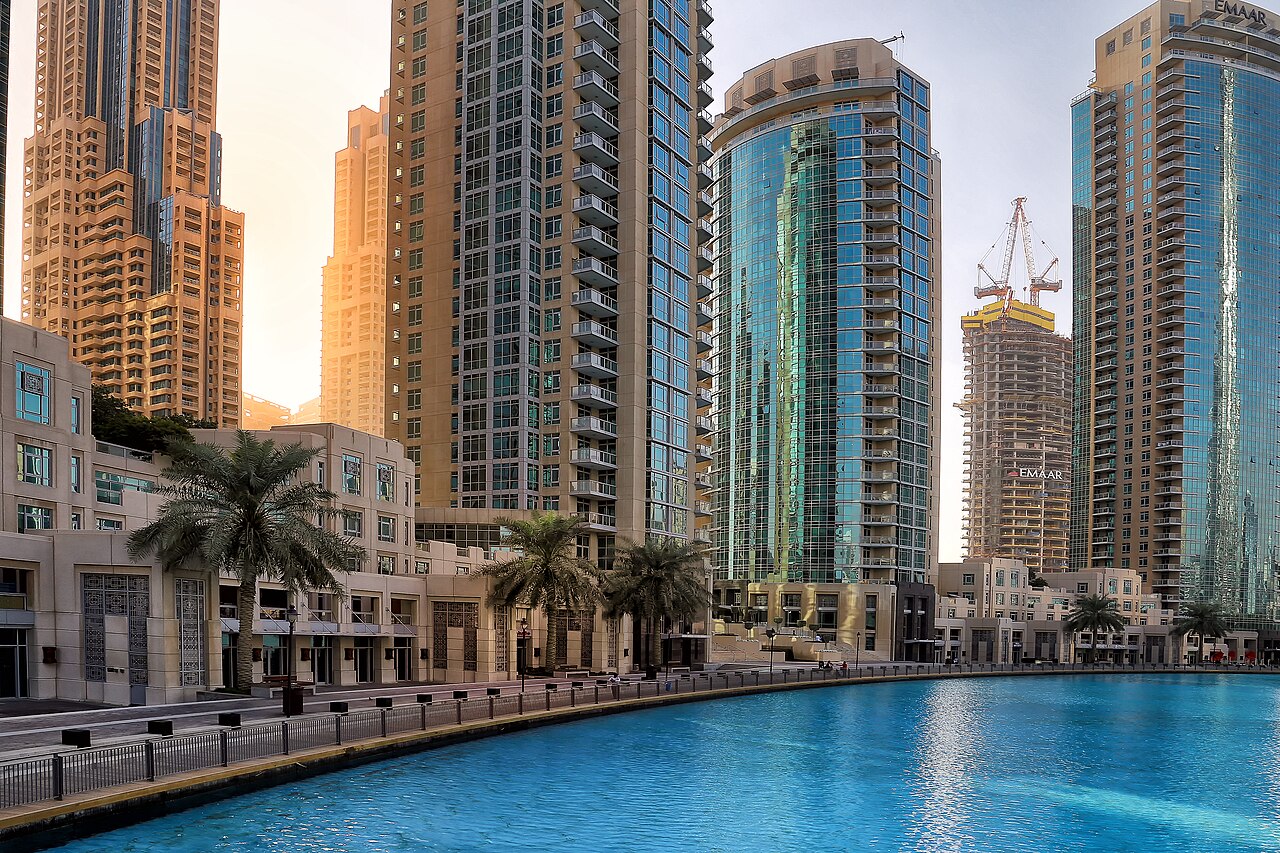
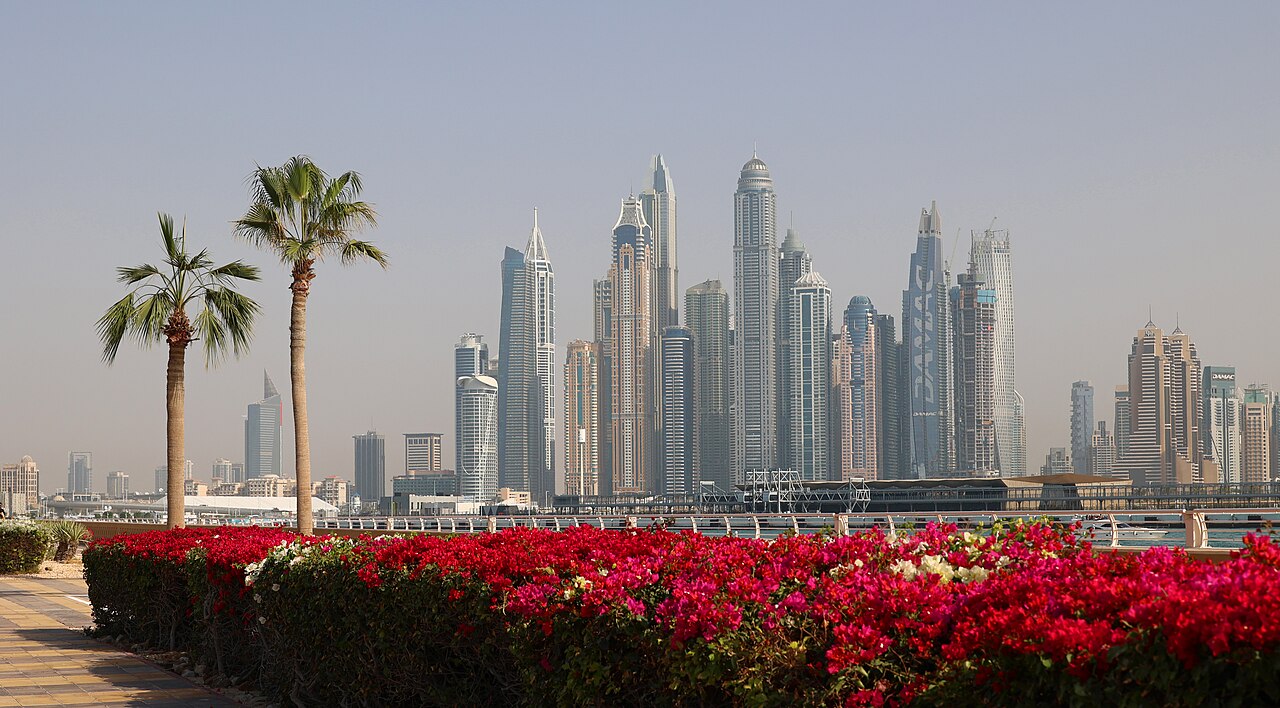
The broader hotel sector suffered a parallel hit. Figures reported by Bloomberg showed hotel occupancy across the United Arab Emirates plummeted to 36 percent during the height of the disruption in March. As international tourists postponed or scrapped travel plans, holiday home operators were left holding thousands of unbooked calendar nights across high-density residential hubs like Dubai Marina, Downtown Dubai, and Palm Jumeirah.
The market response over the subsequent six months has been marked by a clear divergence between property management strategies. While overall tourist arrivals stalled, property managers who adapted quickly by pivoting away from international holidaymakers toward mid-term corporate stays, regional business travellers, and United Arab Emirates residents managed to rebuild their occupancy.
Data from Dubai property manager GuestReady showed that while March and April were its most severely affected months, its portfolio occupancy recovered to an average of approximately 80 percent over the three months leading into autumn. Meanwhile, hotel occupancy in the United Arab Emirates climbed back to 66 percent by August, according to Bloomberg metrics. However, this recovery in filled nights has come at a steep price: significantly lower average daily rates, compressed operating margins, and a structural shift in how owners evaluate property yield.
The February shockwave and the numbers behind the collapse
To understand the severity of the 2026 market reset, one must examine the specific mechanics of the February collapse. In normal operating conditions, Dubai’s short-term rental market relies on a predictable pipeline of long-haul international visitors, European winter sun seekers, and corporate executives booking months in advance. When flight disruptions occurred in late February, that advance booking pipeline vanished overnight.
AirDNA recorded 8,450 cancelled nights on February 28 alone, a figure nearly triple the February baseline average of roughly 3,100 cancellations per night. The 43.8 percent cancellation rate recorded during that period demonstrated how vulnerable high-yield tourist markets are to external geopolitical events. Unlike domestic drive-to holiday destinations, international fly-in markets possess virtually no buffer when airline schedules break down.
The sudden drop in demand triggered an immediate inventory crisis. Professional property management companies that had structured their cost models around premium nightly rates found themselves managing empty units with fixed lease costs, utility expenses, and property owners expecting steady monthly payout guarantees. The shock forced operators to decide whether to hold rates and wait for international confidence to return, or undercut the market to secure whatever local demand existed.
The pivot to mid-term stays and local demand
For First Class Property Management, known as FCPM, survival meant taking immediate, aggressive operational action. According to Luis Santos, co-founder and managing director of FCPM, the company’s internal portfolio hit its absolute low point on March 12, 2026, when portfolio occupancy crashed to 44.2 percent. Rather than holding out for a rapid return of international leisure tourists, FCPM initiated a complete portfolio repositioning.
Santos and his team re-priced and restructured their property listings to target United Arab Emirates residents and corporate business travellers looking for flexible stays lasting between one and six months. The strategy produced an immediate operational turnaround. FCPM’s monthly occupancy rose from 61.9 percent in March to 83.2 percent in April, reaching 89.7 percent by June.
However, Santos emphasized that this rebound did not reflect a recovery in tourist travel. Instead, it represented a temporary migration to an entirely different demand pool. Securing high occupancy required accepting substantial discounts on headline nightly rates. In June 2026, FCPM recorded an average daily rate of AED 270, compared to AED 414 in June 2025. The company’s Revenue Per Available Room reached AED 243 in June 2026, down from AED 337 a year earlier, though still outperforming the wider Dubai market average of AED 188 cited by FCPM.
This trade-off highlighted the core economic mechanism of mid-term management: trading maximum nightly yield for calendar stability and lower operational friction. A monthly or multi-month stay yields lower revenue per night than a high-season holiday booking, but it eliminates frequent turnover cleanings, reduces platform transaction fees, lowers guest acquisition costs, and delivers predictable monthly cash flow directly to property owners who might otherwise face prolonged vacancies.
When a demand shock meets an oversupplied market
While geopolitical disruption caused the initial demand collapse, analysis by market participants reveals that Dubai was already vulnerable due to a growing surplus of holiday homes. FCPM’s analysis of PriceLabs data shows that wider market occupancy in Dubai had dropped from 68 percent in March 2025 to 40 percent in March 2026. In April 2026, market occupancy remained stalled at 40 percent, compared to 87 percent in April 2025. Over the same period, market-wide RevPAR dropped from AED 475 to AED 161.
Santos noted that while the geopolitical crisis triggered the sudden drop in March, the underlying market conditions magnified its impact. Dubai entered the disruption with approximately 3,000 more active holiday home listings than it had twelve months prior. When tourist demand dried up, that expanded inventory pool competed for a drastically reduced pool of prospective guests.
PriceLabs tracking analyzed by FCPM demonstrated the clear lifecycle of inventory contraction during the crisis. Active listings in Dubai peaked at approximately 36,500 in January 2026 before steadily declining to 33,000 in June and 31,800 in July. This reduction of nearly 4,700 active listings in six months represented a significant market correction. Disillusioned property owners chose to delist their units, transition properties into the traditional one-year lease market, or exit the rental business entirely.
The race to the bottom: Guest poaching and rate erosion
The contraction in active supply did not automatically protect remaining operators from severe price pressure. Meera Timsena, general manager of Vihaan Holiday Homes Rental, explained that operational conditions remain challenging across the city, driven by shortened booking lead times and cautious guest spending.
Timsena reported that as operators discounted aggressively to maintain occupancy numbers, consumer behaviour changed markedly. Guests frequently cancelled existing, confirmed bookings after finding competing units in the same building or neighbourhood listed at lower prices. Other guests weaponized the market oversupply by negotiating heavy discounts directly with management companies before confirming reservations.
Continually discounting to secure bookings is not a sustainable strategy; it risks eroding both profitability and the long-term value of the asset.
Timsena warned that continual price discounting presents a dangerous trap for professional managers. While lowering rates may keep units occupied in the short term, it damages property asset values, erodes operating margins, and degrades brand positioning. Vihaan Holiday Homes experienced owner attrition firsthand as market conditions worsened, losing several units from its portfolio as owner confidence waned and property investors re-evaluated their financial returns.
Villas versus condos: The divergence in asset classes
The 2026 downturn also revealed a sharp split in performance based on property type and unit size. While standard studio and one-bedroom apartments in high-density corridors suffered from brutal rate competition, larger residential properties demonstrated remarkable resilience.
GuestReady reported that its villa portfolio operated at close to 100 percent occupancy during the recovery period. Larger properties continued to draw steady demand from traveling families, group trips, and relocating executives who required substantial living space and were less sensitive to minor price adjustments. Across its broader Dubai portfolio, GuestReady saw occupancy averages climb back to approximately 80 percent across the three months leading into late summer.
Owner sentiment within managed portfolios also began to stabilise over the summer. GuestReady reported that its Owner Net Promoter Score reached +44 in July 2026, signalling that transparent communication and proactive yield management helped rebuild owner trust following the spring disruption. The migration of property owners away from short-term rentals into traditional long-term leases slowed down significantly after April as occupancy stabilized.
“When the regional situation stabilises, tourist demand will return fast, Dubai has proven that repeatedly, and the operators who can run nightly and monthly models side by side will take the recovery first.”
What Dubai teaches global operators about geopolitical friction
The events in Dubai during 2026 hold vital lessons for short-term rental operators across major international gateways. High-yield, international fly-in markets carry inherent vulnerability to geopolitical shocks, currency fluctuations, and airline route disruptions. Operators who rely exclusively on short-stay tourist bookings leave themselves exposed when external events halt international travel.
Building operational flexibility directly into pricing strategies and distribution systems is essential for survival. Professional property managers must maintain the technical infrastructure to pivot listings instantly between nightly travel platforms, mid-term corporate housing portals, and local domestic channels. Having direct relationships with corporate mobility managers, regional business networks, and local relocation agencies creates a crucial safety buffer when tourist bookings vanish.
Furthermore, property management contracts must clearly set owner expectations regarding rate volatility and market shifts. Owners who insist on rigid nightly price floors during market contractions end up with vacant properties and zero revenue. As demonstrated by the performance differences between managed portfolios in Dubai, flexibility on rate and stay duration is the primary factor determining whether an operator maintains cash flow or absorbs severe losses.
What hosts should do now
If you operate short-term rentals in high-density urban markets subject to demand volatility, immediate operational adjustments are necessary to safeguard cash flow and preserve asset value.
- Build a hybrid calendar strategy: Configure your dynamic pricing engine to automatically switch properties into 30-to-90-day booking modes during low-demand windows or market shocks, securing baseline income before opening up high-rate nightly slots.
- Diversify distribution channels: Stop relying exclusively on consumer holiday booking portals. Establish active profiles on corporate mobility platforms, regional relocation databases, and mid-term executive housing channels.
- Educate property owners on total yield: Shift owner reporting away from headline nightly rates toward monthly net distribution and occupancy metrics. Demonstrate how lower nightly rates with zero turnover costs produce higher net distributions than empty calendars.
- Establish guest re-shopping protections: Implement strict cancellation windows and non-refundable discount tiers to prevent guests from re-shopping competing units and cancelling existing reservations right before check-in.
- Focus on asset differentiation: If managing standard studio or one-bedroom apartments, compete on work-from-home amenities, flexible check-in terms, and included utilities rather than entering destructive price wars.
The experience of Dubai in 2026 proves that market volatility is an operational reality for international short-term rentals. Operators who build flexible, multi-stay business models will protect their margins, retain property owners, and capture market share while rigid competitors burn through capital waiting for the past to return.
Checked by the standards desk (Eleanor Quist): 89 specifics checked, 78 traced to the source material and the sources added below, 11 general background, none removed.
Sources
- ShortTermRentalz - reported October 21, 2026.
- famliving.com - Dubai Marina Holiday Homes & Monthly Stays | fäm Living.
Read and analysed by the Stay Gazette desk.
Report an error in this story · Corrections policy and log
Read the desk every morning.
The day's crackdowns and platform moves, the money, the design and the stays going viral, plus the desk's verdict, in one short email every morning.
Comments