Vacasa Agrees to Go Public Through a Merger With TPG Pace Solutions
Vacasa said on 29 July 2021 that it had agreed to merge with a TPG acquisition company in a deal the two said implied a pro forma equity value of approximately $4.5 billion. The papers filed with it showed homeowners and rival managers how the company described them to investors.
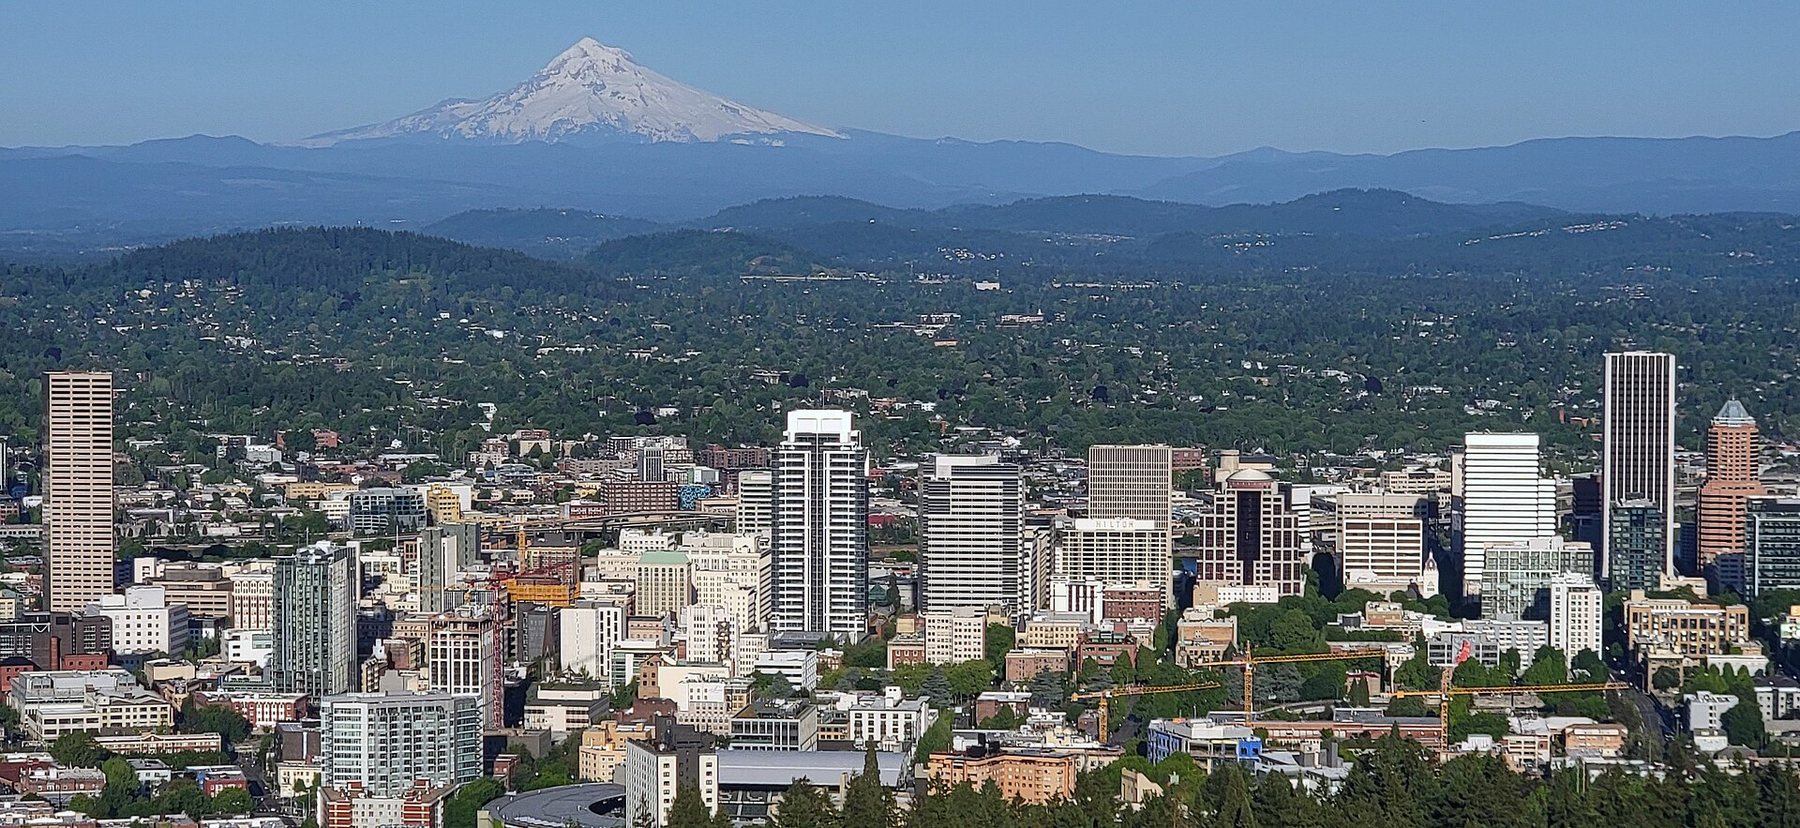
The skyline of downtown Portland, Oregon, with Mount Hood on the horizon, seen from Pittock Mansion and photographed in May 2021. Vacasa's announcement of 29 July 2021 carried a joint dateline of Portland, Oregon, and San Francisco. Photo: Portland skyline from Pittock Mansion May 2021 cropped by Truflip99, CC BY-SA 4.0, via Wikimedia Commons (resized).
From the record. This is a look back at July 2021. The desk wrote it on 11 October 2026 from sources published at the time; Stay Gazette opened in July 2026 and did not report this as it happened.
On 29 July 2021, Vacasa, the vacation rental manager based in Portland, Oregon, said it had agreed to become a publicly traded company by combining with TPG Pace Solutions, a special purpose acquisition company. The two companies said the transaction implied a pro forma equity value for Vacasa of approximately $4.5 billion, and that Vacasa was expected to receive $485 million in gross cash proceeds.
What the companies announced was an agreement to merge. A Form 8-K that TPG Pace Solutions Corp. filed with the Securities and Exchange Commission on 29 July said the Business Combination Agreement was entered into on 28 July 2021. The press release said the transaction was expected to be completed as soon as practicable, subject to approval by the shareholders of TPG Pace Solutions, the effectiveness of a registration statement to be filed with the SEC, and other customary closing conditions.
What the two companies agreed
TPG Pace Solutions' Class A shares were registered on the New York Stock Exchange under the symbol TPGS, and the release said it had raised approximately $285 million to seek an acquisition. Under the agreement, the Form 8-K said, it would merge into Vacasa, Inc., a Delaware corporation that would survive as the parent company of Vacasa.
The cash had two parts, as the release described them:
- up to $285 million of gross proceeds from the cash held in TPG Pace Solutions' trust account;
- a fully committed common equity investment of $200 million, which the release said was anchored by mutual funds, institutional investors and TPG.
The investor presentation filed the same day labeled its table of sources and uses illustrative and said it assumed no redemptions by the acquisition company's shareholders. On those assumptions, $423 million would go to Vacasa's balance sheet and $62 million to estimated fees and expenses.
The release said Vacasa's existing investors, including Silver Lake, Riverwood Capital, Level Equity, Altos Ventures, Adams Street and NewSpring Capital, together with founder Eric Breon and management, expected to roll 100% of their equity and to retain an 88% ownership of the company after the transaction closed.
The presentation's valuation was also labeled illustrative. At a share price of $10.00, it showed an equity value of $4,502 million, net cash of $754 million and an enterprise value of $3,747 million, which it put at 3.7 times projected 2022 revenue of $1,002 million.
Upon closing, the release said, the combined company was expected to be publicly traded under the ticker symbol VCSA. A slide headed as an anticipated timeline placed the shareholder vote and the closing in the fourth quarter of 2021.
The company behind the price
Vacasa's financial statements, filed as an exhibit, said the company collected nightly rent on behalf of homeowners and earned the majority of its revenue from commissions on rent and from reservation-related fees paid by guests.
The release said Vacasa's marketplace connected guests to more than 30,000 vacation homes, bookable on Vacasa.com, the Vacasa Guest App and more than 100 channel partners, including Airbnb, Booking.com and Vrbo.
The release's headline figures for the business were forecasts: approximately $1.6 billion in gross booking value for 2021 on five million nights sold, and revenue growing from $757 million in 2021 to $1.3 billion by 2023.
The reported figures were smaller. The presentation gave as-reported revenue of $299 million for 2019 and $492 million for 2020, and a GAAP net loss of $84.9 million in 2019, $92.3 million in 2020 and $49.3 million in the first quarter of 2021. Preliminary second-quarter results, which the slide said were subject to change, showed revenue of $239 million to $241 million, against what it called an original forecast of $220 million, and a net loss of $16 million to $18 million.
The financial statements also recorded that in May 2020 Vacasa began a reorganization and a reduction of its workforce, primarily in North America, that eliminated approximately 850 positions. The company completed its purchase of Wyndham Vacation Rentals North America on 22 October 2019, for a total purchase consideration of $157.6 million, and of TurnKey Vacation Rentals on 1 April 2021.
What the pitch said about owners and rival managers
Two of the slides dealt directly with people in the trade. One was headed with the claim that homeowners could make 20% or more extra when they switched to Vacasa from other professional property managers. Its chart showed net revenue to the homeowner per unit of $19,700 in the 12 months before joining and $23,800 in the 12 months after, a rise of 21%, with nights sold per unit going from 117 to 154. A footnote said the comparison was on a same-store basis and was based on portfolio additions with an onboarding date from 1 August 2017 to 1 January 2019. The figures were Vacasa's own.
The other described what Vacasa called its portfolio approach. It said the company had onboarded about 6,000 portfolio units since 2018. A separate line on the slide gave an average cost of 1-2x LTM revenue, the finance shorthand for revenue over the preceding twelve months. It described a pipeline of over 350,000 homes managed by 4,500 local professional managers, defined in a footnote as managers in destination markets with over 20 units under management as of 31 March 2021.
The summary of risks told investors that laws, regulations and rules affecting the short-term rental business had limited, and might continue to limit, the ability or willingness of homeowners to rent through Vacasa.
What the companies and the trade press said
Matt Roberts, Vacasa's chief executive, said in the release that the company believed its partnership with TPG Pace Solutions “will help accelerate our growth and the enhancement of our technology offerings for homeowners and guests.”
“Vacasa has established a strong strategic position in a large, fragmented market, providing the company with powerful tailwinds for growth,” said Karl Peterson, the non-executive chairman of TPG Pace Solutions.
Skift, reporting the same day, called Vacasa the largest full-service vacation rental property management company in the United States and said it had disclosed raising $634.5 million in private equity funding. Its reporter, Sean O'Neill, wrote that Vacasa had reached a remarkable milestone, and went on: “Yet the full-service property management sector is crowded, and going public is only the start of the journey.”
The release itself said there could be no assurance that the transactions would be completed, or that the potential benefits of combining the companies would be realized.
The Gazette Verdict, looking back
The July agreement priced Vacasa on what it forecast, and a homeowner or a rival manager had more to learn from the filing than from the headline number. The companies put a pro forma equity value of approximately $4.5 billion on a business whose own presentation showed a GAAP net loss of $92.3 million in 2020. The illustrative valuation was set against projected 2022 revenue of $1,002 million, about double the $492 million reported for 2020. The deal was to bring in $485 million in gross cash if no shareholder redeemed, $62 million of it for estimated fees, while existing holders expected to keep 88%. The same presentation counted 4,500 local managers and more than 350,000 homes as a pipeline, and claimed owners could make 20% or more extra by switching from other professional managers. A host should read a manager's investor deck as a sales document about the host, and check each claim against the host's own statements.
The other side
Vacasa's case was stronger than its losses alone suggest. Revenue as reported grew from $299 million in 2019 to $492 million in 2020, a year in which the company eliminated approximately 850 positions. Preliminary second-quarter revenue of $239 million to $241 million was above the original forecast of $220 million. The existing investors, the founder and management expected to roll all of their equity, and $200 million of the new money was described as fully committed. A manager with that capital could spend on technology and on distribution across more than 100 channels, and the 21% rise in owner revenue was measured on a same-store basis.
What it meant for hosts
None of the documents cited here announced a change to the terms homeowners had with Vacasa. They described a pending deal, and a business that earned most of its revenue from commissions on owners' rent and from fees paid by guests.
What the filing gave owners was a set of the company's own yardsticks. An owner could put a year of statements beside the slide's figures of 117 nights sold before and 154 after, or $19,700 and $23,800 in net revenue per unit, and ask the manager to explain any gap.
For an independent manager with more than 20 units in a destination market, the presentation was notice of being counted. Vacasa told investors there were 4,500 such managers in its pipeline and gave the average cost under its portfolio approach as 1-2x LTM revenue. A manager approached about a sale had the buyer's own published range to start from.
For hosts who listed their own homes, the release showed who else was selling on the same sites: a manager with more than 30,000 homes distributing through Airbnb, Booking.com and Vrbo.
Sources
- Vacasa and TPG Pace Solutions (press release, Exhibit 99.1 to TPG Pace Solutions Corp. Form 8-K, SEC EDGAR), Vacasa, North America’s Leading Vacation Rental Management Platform, to Be Publicly Listed Through Combination with TPG Pace Solutions (29 July 2021).
- U.S. Securities and Exchange Commission (TPG Pace Solutions Corp. filing), Form 8-K, Current Report, date of earliest event reported July 28, 2021 (29 July 2021).
- TPG Pace Solutions Corp. and Vacasa (Exhibit 99.2 to the Form 8-K, SEC EDGAR), Investor Presentation, dated July 29, 2021 (29 July 2021).
- Vacasa Holdings LLC (Exhibit 99.3 to the Form 8-K, SEC EDGAR), Audited consolidated financial statements for 2019 and 2020 and unaudited interim financial statements for the quarter ended March 31, 2021 (29 July 2021).
- Skift, Vacasa to Go Public in $4.5 Billion SPAC Merger on Heels of Vacation Rentals Surge (29 July 2021).
Part of the Stay Gazette record for July 2021. Filed on 11 October 2026; every specific was checked against the sources above, which were read on or before that day. To report an error, write to the desk; see the corrections policy.
Also filed on July 2021
- WorldParis Court Orders Airbnb to Pay 8.08 Million Euros Over 1,010 ListingsA Paris court ordered Airbnb on 1 July 2021 to pay the city 8,080,000 euros for 1,010 listings published without a registration number. From the same day, Airbnb required the number on every entire-home listing in Paris that wanted new short-stay bookings.
- The recordJuly 2021, the whole month
- The recordEvery month on the record