AirDNA Forecasts Its First Drop in Revenue per Rental for 2023
AirDNA's outlook for 2023, published in December 2022, projected a 1.6% fall in revenue per available rental night as listings kept growing faster than demand. Managers were told to plan for a tighter year.
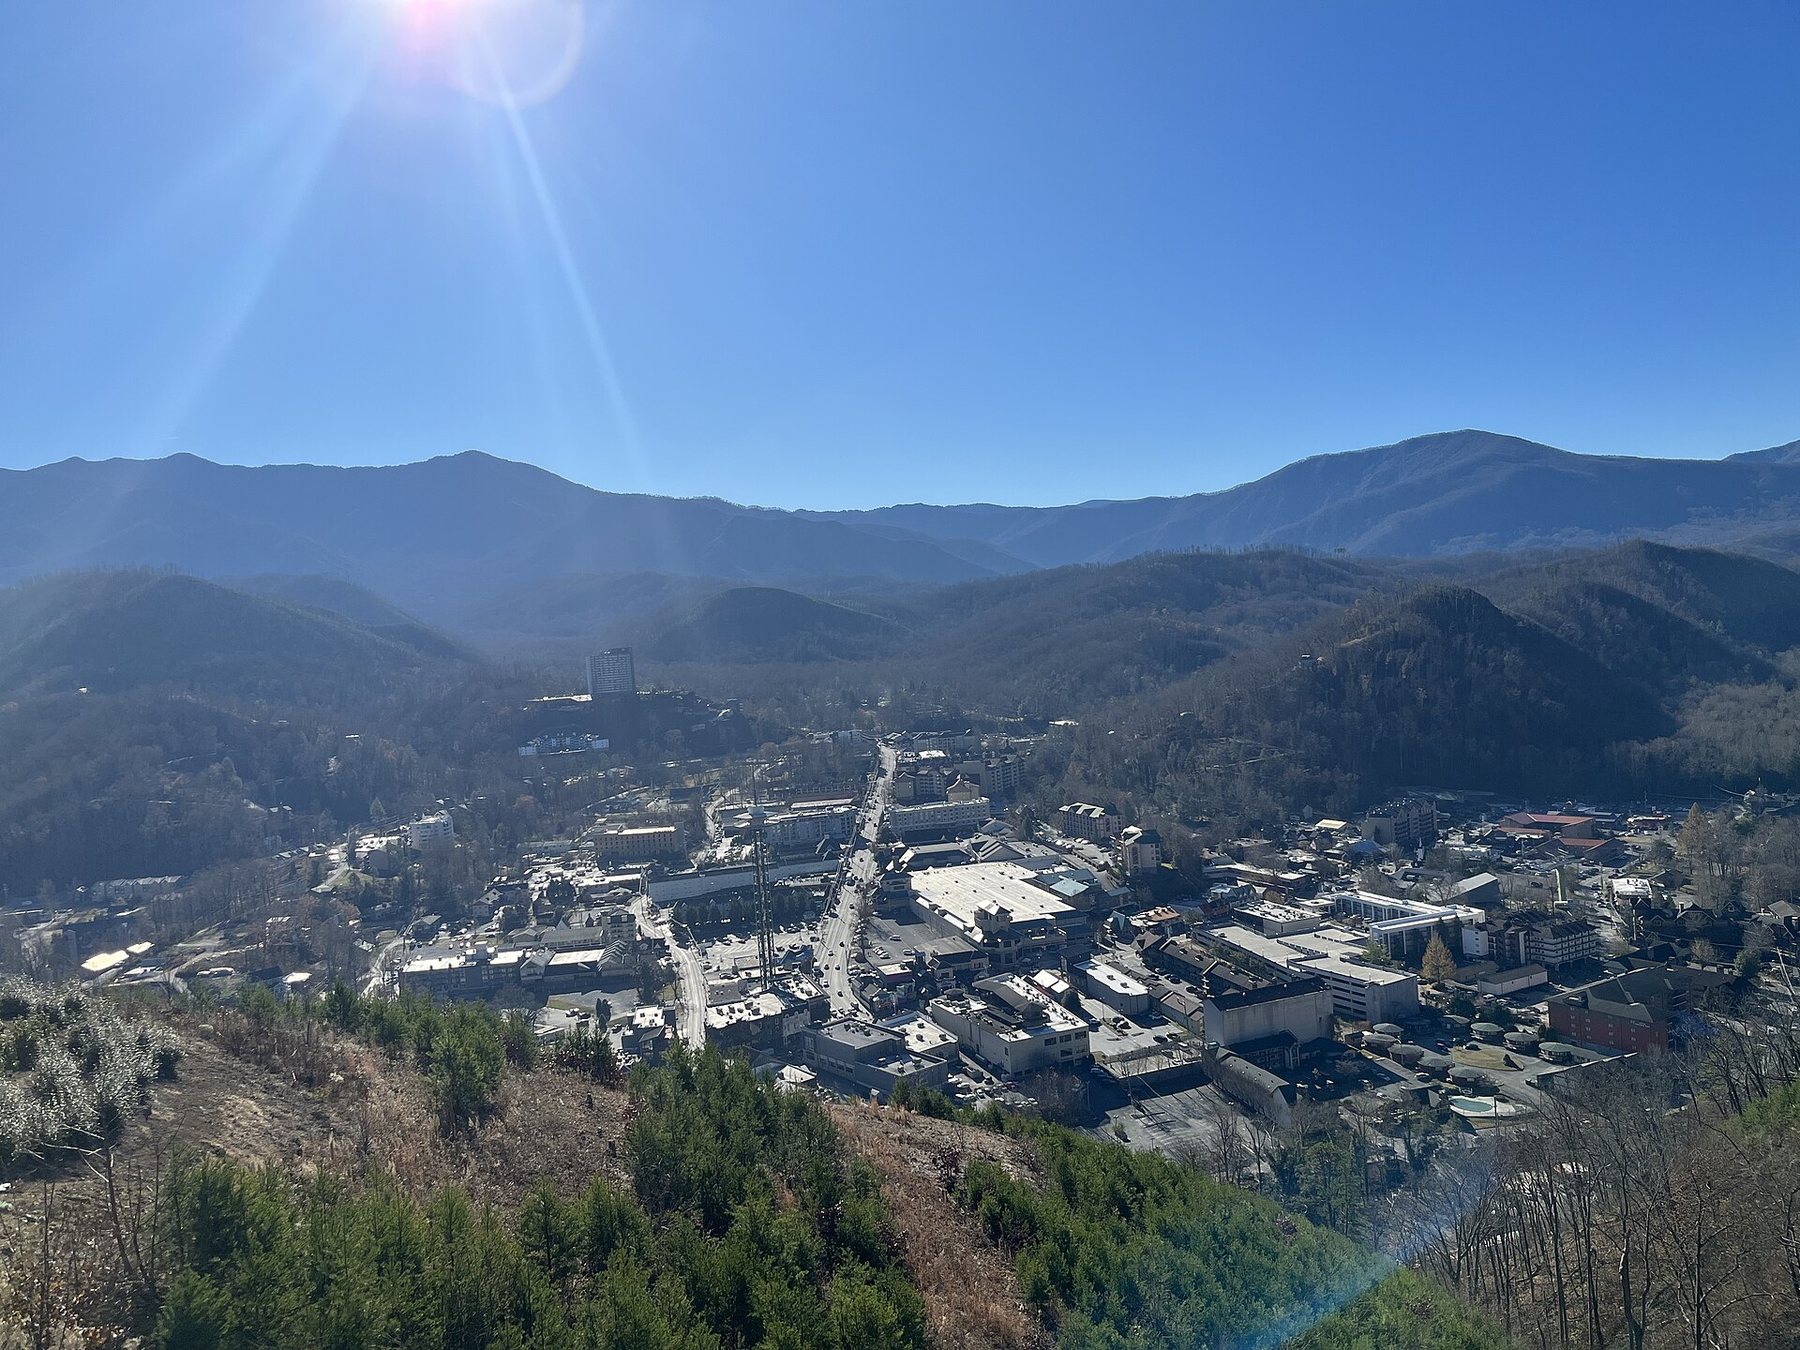
Gatlinburg, Tennessee, seen from the Gatlinburg SkyLift Park on 23 November 2022. AirDNA's outlook said mountain and coastal resort markets would feel the fall in occupancy most. Photo: Gatlinburg, Tennessee viewed from the Gatlinburg SkyLift Park by Sarrail, CC BY-SA 4.0, via Wikimedia Commons (resized).
From the record. This is a look back at December 2022. The desk wrote it on 11 October 2026 from sources published at the time; Stay Gazette opened in July 2026 and did not report this as it happened.
On 13 December 2022, AirDNA published its U.S. 2023 Short-Term Rental Outlook and told the trade to expect something it had not forecast before: less revenue per rental. The data company projected that RevPAR, the revenue a listing earns per available night, would fall 1.6% in 2023, with occupancy down for a second year, to 56.4%.
The cause was supply. AirDNA expected demand to grow 5.5% in 2023, about a quarter of the 21.1% it expected for 2022, while it predicted that listings would increase 9%. Julio Hansoul, AirDNA's global inside sales director, spelled out what that meant in Short Term Rentalz on 19 December: “it is the first negative year-on-year revenue projection we have ever predicted”.
What the outlook forecast
The report set out five numbers for 2023:
- Demand up 5.5%, after an expected 21.1% in 2022.
- Nights listed up 9%, after an expected 25.3% rise in nights supplied in 2022.
- Occupancy of 56.4%. PhocusWire, reporting the outlook on the day it came out, gave the comparison as 58.3% in 2022 and 60.3% in 2021.
- Average daily rates up 1.7%, against inflation that AirDNA put at about 3.6%.
- RevPAR down 1.6%. PhocusWire reported that this followed a 2.1% rise in 2022 and a 27.8% rise in 2021.
AirDNA's own summary of the arithmetic was short. “Overall RevPAR is expected to shrink because the small increase in ADRs will not be enough to offset the decline in occupancy,” the report said. Rates were also losing ground to prices. AirDNA expected average daily rates to rise 5.6% in 2022 while inflation ran at about 7.6%, and it expected the same pattern of higher rates and lower real rates in 2023.
The company did not present this as a bust. It said the industry had reached all-time highs in supply, demand and total revenue, that it had more cause for optimism than despair, and that occupancy would stay above pre-pandemic levels even after the fall.
Why supply kept growing
AirDNA traced the surge in listings to 2021. That year, it said, the gap between what a short-term rental earned and what a new mortgage cost reached a record, and a large number of new listings followed. By the third quarter of 2022, supply was up nearly 25% year over year.
Then the Federal Reserve raised interest rates. Higher mortgage rates on top of high house prices nearly erased that premium, AirDNA said, and left the margin of rental revenue over a new mortgage payment at its narrowest since well before the pandemic. In a post on 14 November 2022, the company noted that U.S. mortgage rates had gone from a low of 2.65% in late 2020 to 7.08% as of 10 November 2022.
AirDNA expected that to slow new supply. It did not expect supply to stop. Citing a Fannie Mae forecast, the report said total home sales would drop 22% in 2023 after a drop of 17.7% in 2022. With buyers and sellers apart on price, owners, particularly owners of second homes, might turn to short-term renting while they waited. Citing Oxford Economics, AirDNA added that the average 30-year fixed mortgage rate was expected to ease from 6.8% in the fourth quarter of 2022 to 5.9% by the end of 2023.
Where the drop was expected
The outlook did not expect the pain to be even. AirDNA said the fall in occupancy would be felt most in the places where occupancy was strongest, particularly coastal and mountain resorts, and that the fall in RevPAR would be felt most in resort locations and small cities. Other city markets might see small gains.
It named exceptions. Areas where supply was held down, such as Maui and Oahu in Hawaii, had seen occupancy rise, as had large cities such as New York and Boston. Across the country, AirDNA said occupancy had declined in the majority of the top 50 U.S. markets. One of its charts showed 31 of the top 50 with falling occupancy in the third quarter of 2022.
The wider economy was the other risk. AirDNA said Oxford Economics predicted at least a mild recession, with GDP down 0.4% over the year in its baseline scenario, against a decline of 2.8% in 2020. Comparing 2022 bookings with 2019, AirDNA put urban and large-city stays 26.7% below pre-pandemic levels, while demand in small towns and rural areas had more than doubled.
What the November numbers showed
A week after the outlook, on 20 December 2022, AirDNA published its review of November. It showed supply already outrunning demand. Available listings reached 1.33 million, up 24.6% year over year. Demand rose 17.0%. Occupancy fell to 51.8% from 54.5% in November 2021. Average daily rates rose 5.7% to $301, and RevPAR was up 0.4%.
New hosts were still arriving. AirDNA counted just over 64,000 new listings in November 2022, the most it had recorded for a November. As of 1 December, bookings for December were pacing 9.1% ahead of the year before, against the 17% growth in demand seen in November.
Hosts had been saying as much from their own calendars. AirDNA's post of 14 November on the #Airbnbust, a term it traced to a viral tweet of 16 October, opened with the complaint that bookings were down, and counted 23% more active rental listings than a year earlier.
What managers told AirDNA
Hansoul's article reported an AirDNA survey of vacation rental managers. Their top concern for 2023 was generating revenue during a potential recession. The second was more competition from other managers and individual hosts. Yet 47 per cent expected their own portfolios to grow by more than 20 per cent, and another 18 per cent expected growth of less than 20 per cent.
Hansoul called the projected fall marginal, and probably to be expected after the growth of the years before. He still called it a downturn.
Since then
AirDNA's review of December 2023, published on 24 January 2024, said the supply of available nights rose 12.6% in 2023 against 6.5% growth in demand, and that occupancy averaged 5.4% lower than in 2022. It said average daily rates fell 1.3% across 2023, while annual revenue reached about $64 billion, its highest yet.
The Gazette Verdict, looking back
AirDNA's December 2022 outlook was a supply warning, and hosts who took it as reassurance read it wrong. The headline number was small, a 1.6% fall in RevPAR. The numbers under it were larger: demand forecast to grow 5.5% while listings grew 9%, after a year in which nights supplied rose an expected 25.3%, and just over 64,000 new listings in a single November. The owners who stood to pay were those in resort markets and small cities, where AirDNA expected the fall to land hardest. Guests gained the choice. Nearly half of the managers AirDNA surveyed still expected their portfolios to grow by more than 20 per cent in that market. The lesson for a host is to budget on what a home earns per available night, and to judge every new property on its own numbers.
The other side
A 1.6% dip is small, and AirDNA said so. By PhocusWire's account of the report, it came after RevPAR rose 27.8% in 2021 and 2.1% in 2022, and the forecast occupancy of 56.4% was still above pre-pandemic levels. Nights stayed were at the highest level ever recorded. AirDNA's argument to hosts was that 2021 was an anomaly: “At AirDNA, we believe 2019 is a fairer benchmark for 2022 than 2021.” On that view the bigger danger in December 2022 was overreaction. A host who cut rates or loosened policies in a hurry because of a marginal forecast could have done the business more harm than the forecast itself described.
What it meant for hosts
For a host or manager planning 2023 in December 2022, the outlook changed the budget. The forecast pointed to slightly lower revenue per home, more competing listings, and rate increases that would not keep up with inflation. In resort markets and small cities, AirDNA expected the squeeze to be felt most.
Hansoul's advice to managers, drawn up with High Rocky Homes, a manager with properties in Colorado and California, was specific:
- Market longer stays and discount them, for a baseline of revenue with less turnover.
- Offer at least three cancellation options, because, he wrote, listings with more flexible terms ranked higher in online travel agency search results.
- Use yield management software, and talk to owners about floor pricing with benchmark data in hand. Those two came from Nadim Tannous, co-founder of High Rocky Homes.
- Vet the revenue potential of every new property before taking it on, and consider trimming listings that take up time without carrying their weight in revenue.
- Market to local, drive-to guests.
Hansoul also expected more enquiries from homeowners in 2023, with higher interest rates, inflation and tighter margins, and told managers to show owners how the rest of the market was performing. AirDNA's advice to individual hosts, in its November post, was to measure a property against 2019 before changing rates or policies out of anxiety.
Sources
- AirDNA, U.S. 2023 Short-Term Rental Outlook | AirDNA (13 December 2022).
- PhocusWire, AirDNA predicts continued recovery for U.S. vacation rentals (13 December 2022).
- Short Term Rentalz, AirDNA: Managing your STR business during an economic downturn (19 December 2022).
- AirDNA, U.S. Market Review: Demand Remains Healthy; Occupancy a Little Under the Weather (20 December 2022).
- AirDNA, Beating the #Airbnbust: 5 Tips for Improving Your Bookings (14 November 2022).
- AirDNA, U.S. Market Review: December Supply and Demand Remain in Balance, Promising a Banner 2024 (24 January 2024).
Part of the Stay Gazette record for December 2022. Filed on 11 October 2026; every specific was checked against the sources above, which were read on or before that day. To report an error, write to the desk; see the corrections policy.
Also filed on December 2022
- WorldEU Court Backs Italy's 21% Tax Withholding on Short-Term RentalsThe EU's top court ruled in December 2022 that Italy could require platforms such as Airbnb to report short-term rental contracts and withhold 21% of the rents they collected. It rejected Italy's demand that platforms based elsewhere appoint a tax representative in Italy.
- The recordDecember 2022, the whole month
- The recordEvery month on the record