Sonder Agrees to Go Public Through a Merger With Gores Metropoulos II
Sonder signed a merger agreement with a Nasdaq-listed special purpose acquisition company and put its unaudited numbers on the public record. The companies expected the deal to close in the second half of 2021.
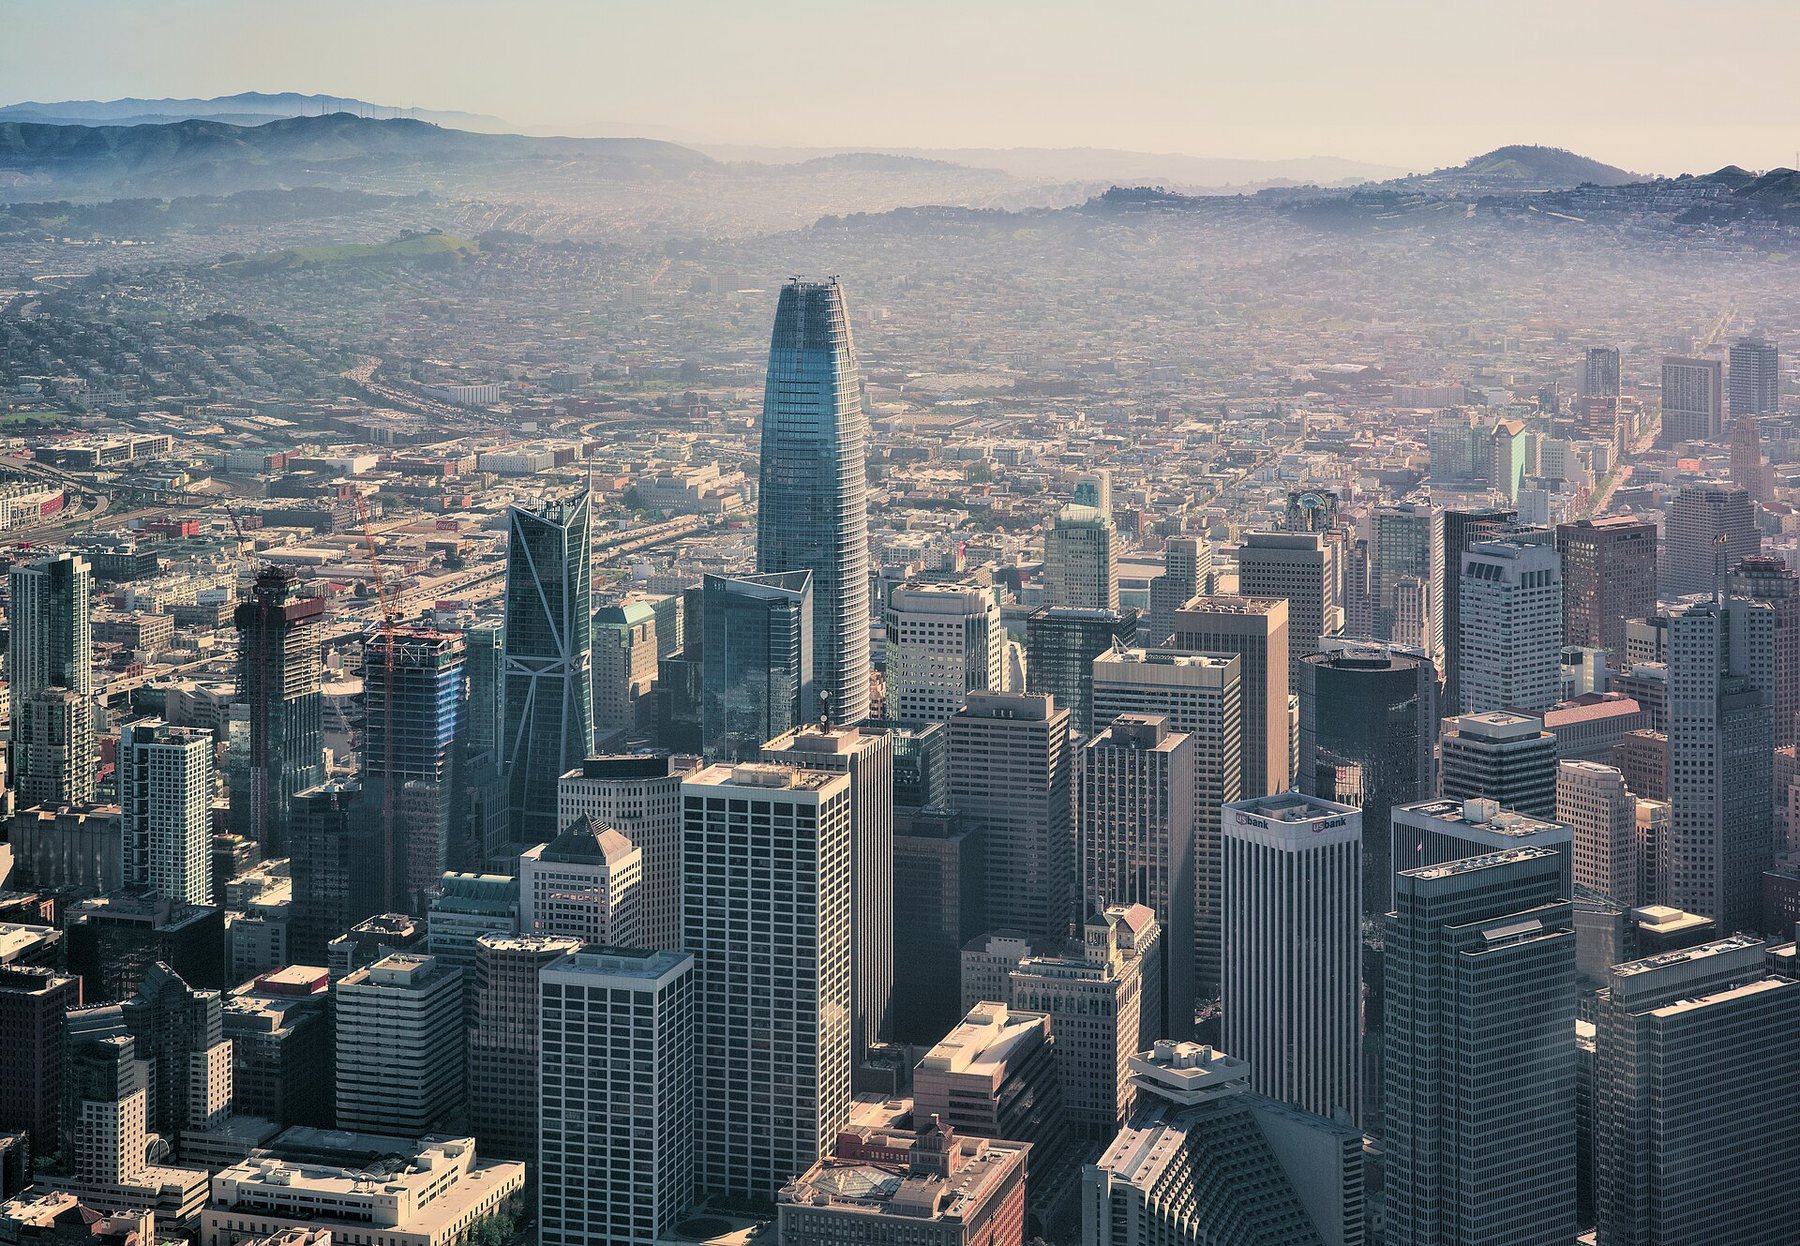
Downtown San Francisco seen from the air from the north, photographed on 14 April 2018. Sonder's merger announcement of 30 April 2021 gave San Francisco as the company's headquarters. Photo: Aerial view of downtown San Francisco from the north dllu by Daniel L. Lu (user:dllu), CC BY-SA 4.0, via Wikimedia Commons (resized).
From the record. This is a look back at April 2021. The desk wrote it on 11 October 2026 from sources published at the time; Stay Gazette opened in July 2026 and did not report this as it happened.
On 30 April 2021, Sonder Holdings Inc., the San Francisco company that leases space from developers and property owners and rents it to guests by the night, week or month, said it had agreed to become a publicly listed company by merging with Gores Metropoulos II, a special purpose acquisition company whose shares traded on the Nasdaq. The merger agreement was signed on 29 April 2021, and the boards of both companies unanimously approved it that day, according to the report Gores Metropoulos II filed with the Securities and Exchange Commission.
The two companies said the combined business was expected to have a pro forma enterprise value of $2.2 billion and more than $700 million of net cash at closing. The deal was to bring $650 million of cash proceeds from Gores Metropoulos II before expenses, including a fully committed private placement of $200 million. They expected it to close in the second half of 2021. On the day of the announcement it was a signed agreement: the listing depended on a stockholder vote and other conditions still to be met.
What the two companies agreed
Sonder's stockholders were to be paid in stock. The filing said that under the merger agreement they would receive a number of Gores Metropoulos II common shares equal to $2,176,603,000 divided by $10.00, the value each share was deemed to have. The press release said existing Sonder stockholders would retain 74% ownership in what it called the pro forma company.
The cash had two sources. Gores Metropoulos II held $450 million in its trust account. On 29 April, investors agreed to buy 20,000,000 of its shares at $10.00 each in the private placement. The release said that $200 million placement was led by an affiliate of The Gores Group and included Fidelity Management & Research Company LLC, funds and accounts managed by BlackRock, Atreides Management, LP, entities affiliated with Moore Capital Management, Principal Global Investors, LLC, and Senator Investment Group. Sonder had also raised $165 million in a March 2021 convertible notes offering led by Moore Strategic Ventures.
The release said the cash would be used to fund operations and to support growth initiatives. It also said all references to available cash were subject to any redemptions by the public stockholders of Gores Metropoulos II and to the payment of transaction expenses.
Closing required, among other things, the approval of Gores Metropoulos II's stockholders. A party could terminate the agreement if the merger had not been completed by 28 October 2021 and its own breach had not caused the delay. Francis Davidson, Sonder's co-founder, was to continue as chief executive.
How the $2.2 billion was built
The $2.2 billion was an enterprise value: the value of the shares less the net cash the combined company was expected to hold. The investor presentation in the filing showed the steps in a table it labeled an illustrative pro forma valuation. Assuming a nominal share price of $10.00, it put the combined company's equity value at $2,939 million. It subtracted $739 million of pro forma net balance sheet cash to reach an enterprise value of $2,200 million, and gave an implied multiple of 3.6 times Sonder's projected 2022 revenue of $610 million.
The same slide, under the heading of illustrative post-transaction ownership, divided the $2,939 million among the owners: $2,177 million for existing Sonder shareholders, $450 million for the public shareholders of Gores Metropoulos II, $200 million for the private placement investors and $113 million for the sponsor of Gores Metropoulos II. A note on the slide said the split excluded the effect of warrants and of an earn-out to existing Sonder shareholders, which the filing put at up to 14,500,000 shares.
Short Term Rentalz reported on 30 April that Sonder had last been valued at around $1.3 billion, after a $170 million Series E funding round in the summer of 2020, and that when news of the talks emerged three weeks earlier the company had been rumored to be set for a valuation of $2.5 billion or more.
What the filing showed about the business
Sonder operated more than 300 properties across 35 markets in eight countries, the release said. The presentation gave its recent results. It labeled the 2019 and 2020 financials unaudited, preliminary and subject to adjustment:
- Revenue was $142.908 million in 2019 and $116.153 million in 2020.
- The net loss was $178.767 million in 2019 and $240.663 million in 2020.
- Landlord payments in 2020 were $119.347 million, more than the year's revenue. That line came from a table the presentation described as management's presentation of the financials.
- About 4,000 units, live and contracted, were dropped from the portfolio in 2020, about 30% of the total portfolio in January 2020.
- Sonder ended 2020 with 4,565 live units.
The growth figures in the presentation were Sonder's own projections, and its disclaimer said projected numbers were used for illustration and might not reflect actual results. Sonder projected revenue of $172.831 million in 2021, $610.450 million in 2022 and $3,995.280 million in 2025. The release put the 2025 figure at approximately $4 billion. It projected 8,133 live units at the end of 2021 and 77,234 at the end of 2025. Its projected adjusted EBITDA, which the presentation called a non-GAAP metric, was a loss of $256.843 million in 2021 and of $205.845 million in 2022, then a positive $24.201 million in 2023.
What the companies said
Davidson called the deal “a natural extension of our longstanding relationship that will enable us to accelerate our growth on the path to build the iconic 21st century brand in hospitality.”
Alec Gores, chairman and chief executive of The Gores Group and chief executive of Gores Metropoulos II, said Sonder “has already proven the resiliency and scalability of its business and has tremendous potential to continue expanding globally amid tailwinds created by the impending travel recovery.”
The cautions on the record
Bisnow reported on 30 April that Sonder's practice of master leasing blocks of apartments or entire buildings had left some landlords with large vacancies when the pandemic forced the company to pull back some of its operations, and that in at least two cases landlords had sued. Bisnow added that Sonder representatives had said in January 2021 that the company kept occupancy above 70% through 2020.
Gores Metropoulos II said in its filing that it was aware of the statement that SEC staff released on 12 April 2021 on accounting and reporting considerations for warrants issued by special purpose acquisition companies, and that it was evaluating the statement's applicability and impact on the financial statements it had already filed. The release listed that statement among the deal's risks: it could require Gores Metropoulos II to restate its historical financial statements and could delay the merger.
The Gazette Verdict, looking back
Sonder's April 2021 deal asked public investors to pay for a forecast, and the people who rent out homes and buildings should have read it as one. The $2.2 billion pro forma enterprise value was an implied 3.6 times projected 2022 revenue of $610 million, when unaudited 2020 revenue was $116.153 million and the net loss was $240.663 million. Landlord payments in 2020 were larger than revenue, and about 4,000 units had been dropped. One slide set out who stood to gain: at a nominal $10.00 a share, $2,177 million of stock for existing Sonder shareholders and $113 million for the sponsor, with $650 million of cash for the company before expenses and redemptions. For a host or an owner, the lesson is to read an operator's filed numbers before its pitch, and to ask what happens to the lease in a bad year.
The other side
The best case for the deal is that Sonder had come through a pandemic year and could show it. Its representatives said it kept occupancy above 70% through 2020, Bisnow reported. The $200 million private placement was fully committed, with Fidelity Management & Research Company and funds managed by BlackRock among the investors who agreed to buy at $10.00 a share. The projections were presented as projections, the 2019 and 2020 figures were labeled unaudited, and the risks were listed. The release said the cash would fund operations and growth, and the deal offered $650 million before expenses while existing stockholders were to retain 74% of the pro forma company.
What it meant for hosts
For a host or a landlord, the announcement of 30 April 2021 was a plan. The merger had not closed and the stockholder vote had not been held.
What a host gained was a public set of numbers on a competitor. Sonder operated more than 300 properties in 35 markets and projected growth from 4,565 live units at the end of 2020 to 8,133 a year later. A host competing for the same guests in one of those markets could plan on a better-funded rival, if the deal closed and the projection held.
For an owner or developer weighing a lease with Sonder or an operator like it, the filing was the place to check the pitch. It showed 2020 landlord payments above 2020 revenue, about 4,000 units dropped in 2020, and results not yet audited. Bisnow's report of lawsuits from landlords in at least two cases was a reason to ask, before signing, what the lease said about early exit and who carried the rent in a downturn.
Sources
- Sonder Holdings Inc. and Gores Metropoulos II, Inc. (joint press release, filed with the SEC as Exhibit 99.1), Sonder, a Next-Generation Hospitality Company, to Be Publicly Listed Through Combination With Gores Metropoulos II (30 April 2021).
- U.S. Securities and Exchange Commission (Gores Metropoulos II, Inc. filing), Gores Metropoulos II, Inc. current report, Form 8-K, date of report April 29, 2021 (30 April 2021).
- U.S. Securities and Exchange Commission (Gores Metropoulos II, Inc. filing, Exhibit 99.2, which the Form 8-K dates April 30, 2021), Investor Presentation April 2021 (30 April 2021).
- Bisnow, Short-Term Rental Company Sonder To Go Public Through SPAC Deal At $2.2B Valuation (30 April 2021).
- Short Term Rentalz, Sonder to go public via SPAC merger worth $2.2bn (30 April 2021).
Part of the Stay Gazette record for April 2021. Filed on 11 October 2026; every specific was checked against the sources above, which were read on or before that day. To report an error, write to the desk; see the corrections policy.
Also filed on April 2021
- PlatformsGuesty Raises $50 Million and Buys Your Porter Weeks After Buying MyVRGuesty raised $50 million in a round led by a fund advised by Apax Partners and announced its second purchase of a property management software company in a month. A principal at the lead investor called it the platform to consolidate the market.
- The recordApril 2021, the whole month
- The recordEvery month on the record